Summer 2025 Newsletter: The One Big Beautiful Bill Act, Social Security Timing, and Protecting College Students
Summer is in full swing, and over the past few months, three things have been climbing rapidly: the temperature outside, my golf scores, and the stock market since the early April lows. Only two of them are worth celebrating.
Welcome to the latest edition of our Swan Quarterly Newsletter. Each quarter, we are committed to bringing you timely topics from recent conversations with clients and actionable strategies to help you navigate the ever-changing financial landscape. In this edition, we cover: the One Big Beautiful Bill Act, our approach to claiming Social Security benefits, and an overlooked medical protection for college attendees. As always, our goal is to provide you with the tools and knowledge to make confident, informed decisions. We're here to help you stay ahead, no matter what the markets or life may bring. Thank you for allowing us to be part of your financial journey. Let's dive into this quarter's updates and opportunities!
The Big Beautiful Breakdown
President Trump officially signed the One Big Beautiful Bill Act (OBBBA) into law on July 4, 2025. The bill runs 940 pages, so we'll focus on summarizing the impact on personal income tax returns. Here are nine key highlights.
Extension of existing tax rates: the bill permanently keeps the lower tax rates put in place in 2017. If it hadn't passed, rates would have gone up significantly for married filing jointly: 12% to 15%, 22% to 25%, 24% to 28%, 32% to 33%, and 37% to 39.6%.
Increased standard deduction: the standard deduction from the TCJA is now permanent. For 2025: $15,750 for single filers, $23,625 for head of household, and $31,500 for married filing jointly.
SALT deduction: the State and Local Tax deduction cap increased from $10,000 to $40,000 in 2025 for married filing jointly, especially meaningful for our Minnesota clients given the state's income and property taxes.
Senior deduction: individuals 65 and older with income up to $75,000 (or $150,000 married filing jointly) can claim a new federal deduction of $6,000 (single) or $12,000 (joint), phasing out between $75,000 to $175,000 (single) or $150,000 to $250,000 (joint), available through 2028. Tax on Social Security benefits itself was not eliminated, despite rumors.
Charitable deduction: non-itemizing retirees can now deduct up to $1,000 (single) or $2,000 (joint) in charitable contributions through 2028.
Medicare and healthcare: retirees with Medicare coverage are largely unaffected directly, though broader healthcare spending changes could add indirect pressure over time.
Bonus depreciation: 100% bonus depreciation is back, effective for properties bought after January 20, 2025, great news for real estate investors and business owners.
Tips and overtime pay: this creates an above-the-line deduction (not a full tax exemption) through 2028, up to $25,000 for tips if married ($12,500 single), and a similar amount for overtime, phasing out at $300,000 MAGI married ($150,000 single).
Trump Accounts: for children born between January 1, 2025 and December 31, 2028, the federal government will seed $1,000 into a new tax-advantaged account. Parents and others can contribute up to $5,000 annually, invested in index funds, with distributions available at 18 for education, a small business, a farm, or a first home.
If you have questions on how any of these changes affect your situation, don't hesitate to reach out.
The Optimal Time to Start Social Security
A client recently told us, "Well, my brother's advisor said he should wait until 70 to start collecting." It's a common piece of advice, and delaying to age 70 does produce the largest monthly benefit. But we don't believe in one-size-fits-all guidance, every retiree's situation is different.
Just scratching the surface, here are a few factors we weigh: mortality versus longevity assumptions, including your family's health and longevity history; opportunity cost, weighing the value of a dollar now versus later against your broader retirement income and goals; how your current and future income needs interact with your portfolio balance, since Social Security can act as a buffer in poor market environments; spousal and survivor benefits, which matter more with a significant age or earnings gap between spouses; and tax considerations, since Social Security is generally taxed as ordinary income and coordinating withdrawals with your bracket can make a big difference.
The "best" age to claim isn't always about the biggest monthly paycheck, it's about what's most optimal for your full retirement plan. If you or someone you know is weighing this decision, a conversation with us can help clarify what actually matters for that specific situation.
College Students: Plan Ahead for Emergencies
A practical item for parents and grandparents of college-age children. Once a child turns 18, the law generally treats them as an adult, which means parents lose the automatic right to access their medical records, even in an emergency. We've heard from clients about situations where a minor health issue turned into unnecessary anxiety simply because a physician couldn't share information with a parent hundreds of miles away.
Two forms are worth considering before the school year starts: a HIPAA authorization form, which many students already fill out at their primary care office and which can often be completed online too, ideally in both your home state and the state where they attend school, and a FERPA authorization, which a student can sign to allow a campus health clinic to share information with parents in an emergency.
We're financial planners, not medical or legal professionals, so this is meant as a helpful heads-up rather than legal guidance. Please check with a physician or attorney with specific questions.
If You're Still Reading...
Meet Donny: for anyone who hasn't had a chance to meet our newest partner yet, reach out any time to set up an introduction.
We're grateful for referrals, and currently have capacity to take on a few additional clients. If someone in your life could benefit from the kind of planning we do, we'd be glad to help.
As part of his godfather/uncle duties, TJ has been moonlighting as a successful youth golf instructor. If anyone needs a swing lesson this summer, look no further!
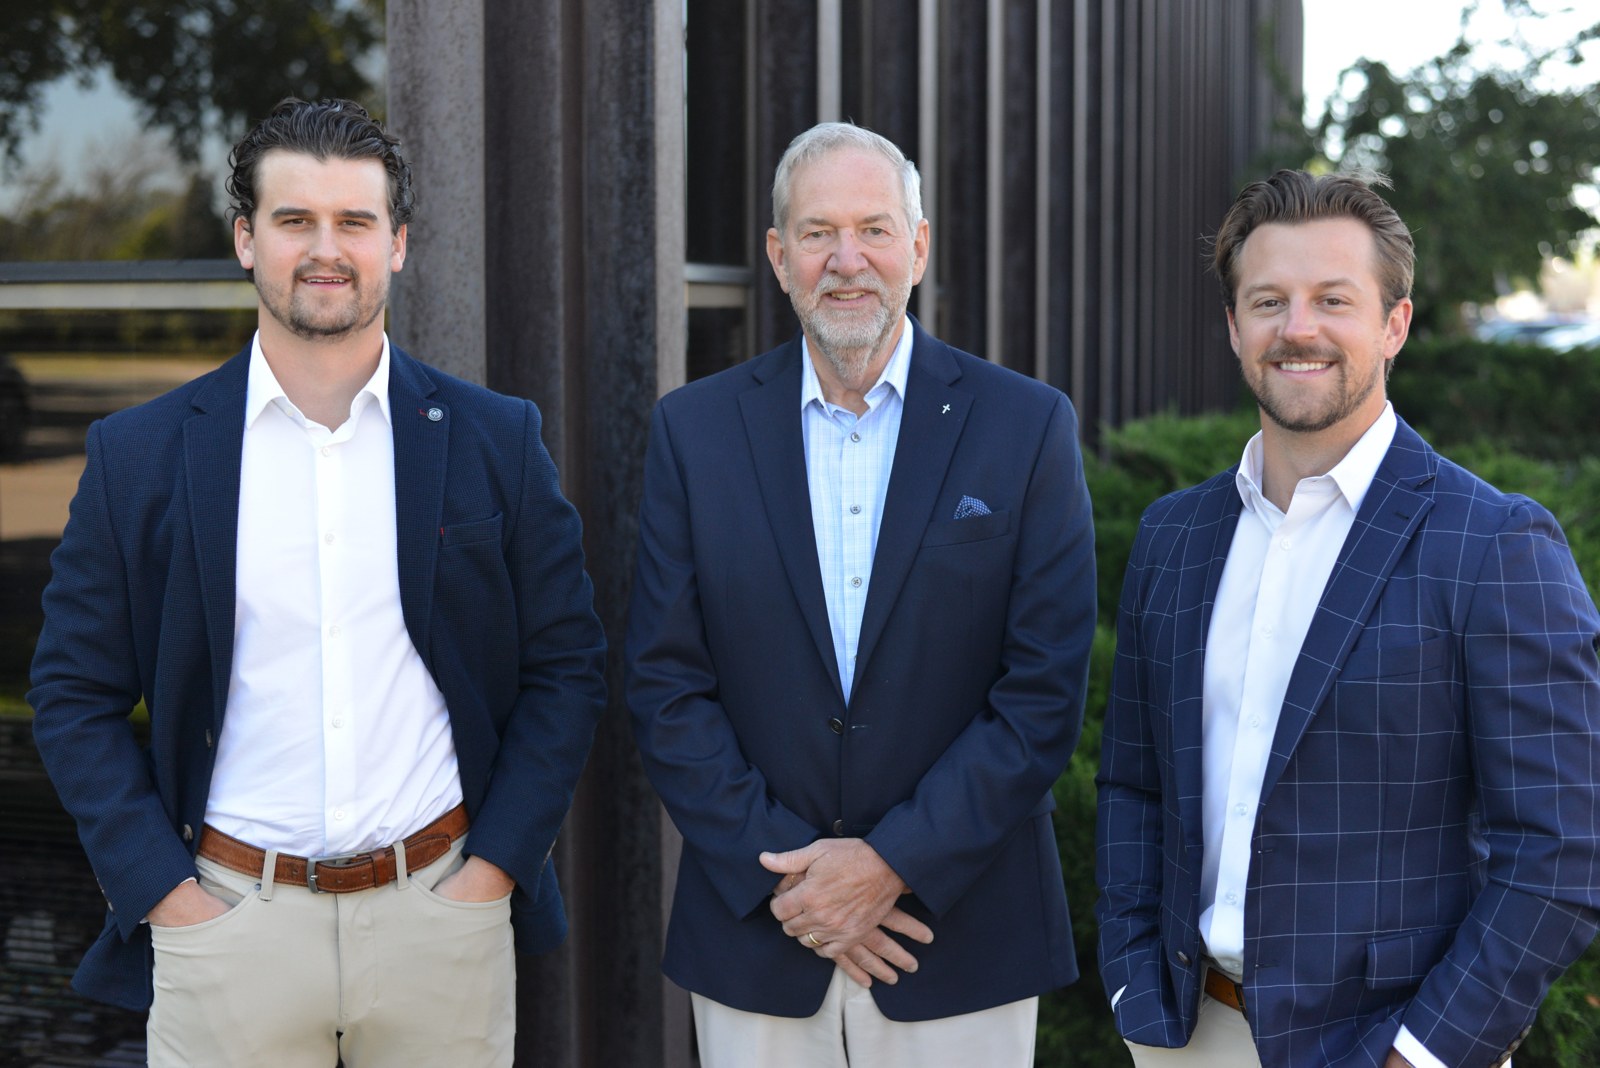
Mike Mahalich, TJ Bruce, Donny Stewart, Paul Klein
Book a consultation
Talk through your own situation with an advisor on a free 15 minute call.
Schedule a consultation