Fall 2024 Newsletter: Election-Year Markets and the Expiring TCJA Tax Cuts
We couldn't be more excited to introduce you to the first edition of our brand-new Quarterly Newsletter, your go-to resource for staying informed and empowered on all things personal finance. The most exciting part about the newsletter is that it's created in part by you, our beloved clients, inspired by client conversations we've had over the last three months.
In each edition, you'll find timely content on financial insights, market updates, industry news, and lifestyle tips, all from our clients, written for our clients. Our aim is to break down complex financial topics into clear, digestible insights you can apply to secure and grow your wealth. Say goodbye to the noise in the media landscape and hello to fresh, simple perspectives on how it relates to your finances.
From retirement planning and tax strategies to economic trends and market updates, this newsletter is designed to keep you informed and confident as you navigate your financial journey. Thank you for joining us as we continue to enhance your journey toward financial clarity and success. Cheers to a brighter financial future.
The Evolution of the iPhone and the Election
"But Paul, TJ and Mike, this election is different!"
Hard to believe, but it's been more than 17 years since Steve Jobs unveiled the first iPhone on June 11, 2007 (Dow 11,405). The iPhone revolutionized not just phone calls, but transformed, in ways unimaginable at the time, every aspect of our lives, from text messages to getting a ride, from social media to banking, from email to how we set the temperature in our homes. Today's phones are roughly 20 times more powerful than the first iPhone.
But what does this have to do with elections? Whatever the outcome of the election, whatever fallout follows, and whatever policies come from the new President and Congress, Apple and the tens of thousands of other companies in the United States will continue finding new and innovative ways to make better, faster, and more profitable products. As long-term investors, we won't so much as blink an eye.
America is the most productive country in the history of the world, and arguably the most innovative. The American economy will not cease to strive for further development and creation of new ideas, regardless of who is President. So if (and when) your friends and family bring up the election over the holidays, keep taking it with a grain of salt when it comes to financial markets. If you want a deeper dive into elections and market performance, read on.
A Deeper Dive into the 2024 Elections and the Markets
The presidential election is right around the corner, and we've had a few clients ask about the impact it may or may not have on the markets. While nobody can know for sure, historical data can help us navigate the perceived uncertainty.
While the S&P 500 historically has posted lower total returns in election years versus non-election years (data from 12/31/1927 to 12/31/2023), results have shown an average yearly gain of 11% and a median yearly gain of 14% during election years, perhaps surprising, and not too shabby! That said, the broader benchmarks have exceeded the average return year to date, so it wouldn't completely shock us to see a pullback in the following few months.
Historically, there's been a spike in volatility in both equity and bond indices before and close to election days, which we saw in early October, about 30 days before Election Day. Of course, past performance is not indicative of future results, but historical data has its place in analysis, history doesn't often repeat itself, but it can rhyme.
Once traders and investors navigate through October and make it past Election Day, a dose of uncertainty is removed once a winner is declared. According to 90 years of data, volatility tends to fall sharply in December of election years, so there's often light at the end of the volatility tunnel, a pattern sometimes nicknamed the "Santa Claus Rally."
In today's digital age, we live in a world riddled with negativity, whether it's the local nightly news, headlines on your favorite media site, or your cousin's economic outlook, there's no shortage of "expert" opinions, especially during election years. For some perspective, remember what you've endured investing through in just the past five years alone: COVID, the Russia/Ukraine war, the highest inflation rate in 40 years, the fastest rate-hike increase in decades, the Silicon Valley Bank collapse, and the Israel/Gaza war.
You don't have to look very hard for reasons to sell stocks. However, staying invested throughout market cycles, including presidential election cycles, has been the most proven way toward success in the market. Please know that we're here as a resource for you if you have any financial questions or concerns this election season.
Expiration of the TCJA Tax Cuts... An Opportunity for Keen Investors?
It's not what you make, it's what you keep. Taxes can be a drag on your portfolio, everyone eventually has to pay the proverbial piper, but we don't want our clients leaving a tip for the IRS.
Starting in 2018, the Tax Cuts and Jobs Act (TCJA) temporarily reduced income tax rates almost across the board. Because Congress was unwilling to match these tax cuts with spending cuts, the law was written to expire at the end of 2025. That means at the end of next year, someone with a taxable income of $100,000 will see their tax bill go up by approximately $3,000, not life-changing, but not chump change either.
Even if the new President and Congress wanted to extend these tax cuts, they'd have to act quickly to negotiate and pass the law before year's end, not an outcome we'd be willing to bet $3,000 on, especially with a ballooning national debt and a looming Social Security/Medicare funding shortfall.
Our best option for hedging this bet is looking for opportunities to pay taxes at today's known rates versus risking a higher rate in the future, sometimes called "paying the devil you know versus the devil you don't." It's relatively simple, but not easy, since it requires voluntarily paying taxes today instead of kicking the can down the road. No one knows where tax brackets will be in 10 or 20 years, but tax brackets in America are historically lower on average right now. It's our job as your financial planners to give you this context to help you decide whether to take advantage of the opportunity at hand.
2024 Tax Brackets
| Tax Rate | Single: Taxable income over | Single: But not over | Married Filing Jointly: Taxable income over | Married Filing Jointly: But not over |
|---|---|---|---|---|
| 10% | $0 | $11,600 | $0 | $23,200 |
| 12% | $11,601 | $47,150 | $23,201 | $94,300 |
| 22% | $47,151 | $100,525 | $94,301 | $201,050 |
| 24% | $100,526 | $191,950 | $201,051 | $383,900 |
| 32% | $191,951 | $243,725 | $383,901 | $487,450 |
| 35% | $243,726 | $609,350 | $487,451 | $731,200 |
| 37% | $609,351 | no limit | $731,201 | no limit |
If You're Still Reading...
We finally got a team picture! Navy blue is our favorite color.
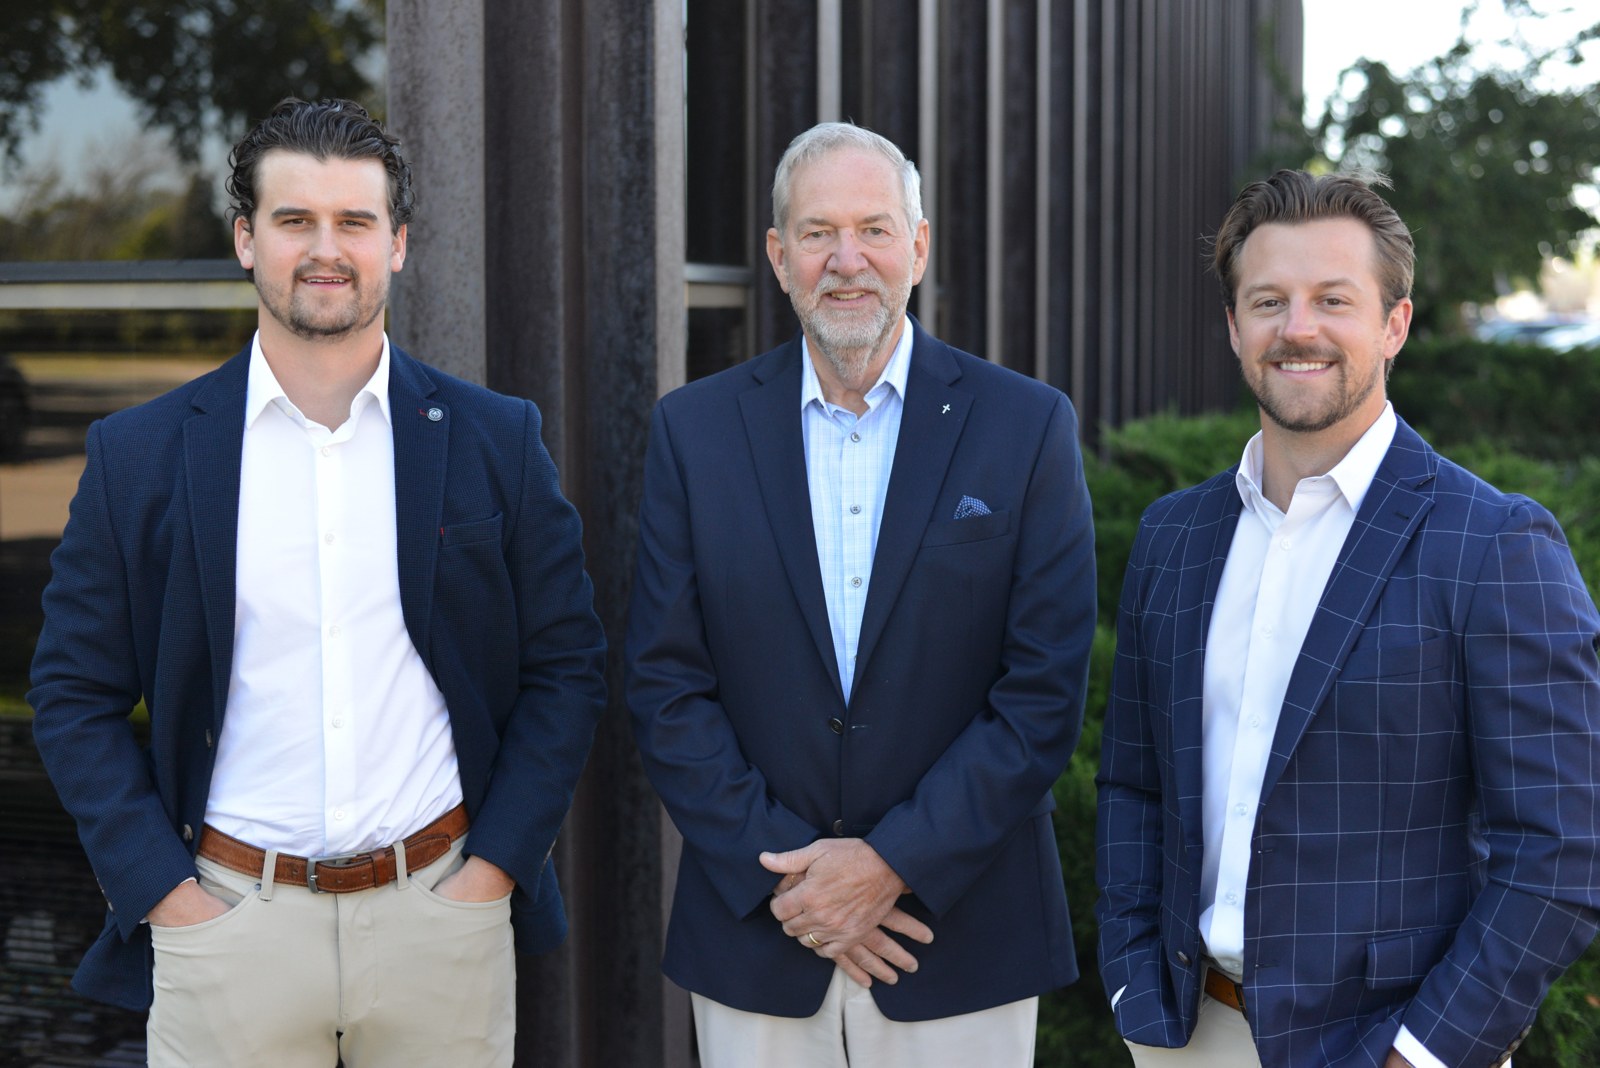
As we wrap up the first edition of our Quarterly Newsletter, thank you for joining us on this journey to financial education and clarity. We're excited to continue sharing insights, strategies, and updates with you in the months ahead. If you have any questions or topics you'd like us to cover, please don't hesitate to reach out, we're here to help.
Onward,
Mike, TJ and Paul
Book a consultation
Talk through your own situation with an advisor on a free 15 minute call.
Schedule a consultation